Let’s start with the good news.
The industry is having its best year since COVID. Box office is up roughly +20% over last year and has recovered to about 93% of 2019 — the last pre-COVID year and second-highest grossing year on record.
We’re not all the way back. But make no mistake, this is HUGE progress and something our industry should feel very good about.
At the same time, dig beneath that 93% and a very different story emerges — particularly for smaller, independently owned theatres.
Overall industry attendance remains approximately -39% below 2019, but there are also -14% fewer screens operating today. Spread those admissions across fewer screens, add a +24% increase in average ticket price, and something pretty remarkable happens:
Industry gross per screen is actually 7% ABOVE 2019.
Now look at 1–4 screen theatres.
Their screen count is down -18%, not dramatically different from the industry. But attendance per screen is down -44% — twice the industry's -22% decline. And gross per screen is down -10%, compared with the industry's +7% increase.
That’s a 17-percentage-point gap.

Industry vs. 1–4 screen theatres, YTD through 39 weeks. | Estimates ATP 80% vs Industry
The Big Difference: People Walking Through the Door
So, this isn't simply about fewer theatres or fewer screens. And it isn't about dramatically different ticket-price growth.
The big difference is people walking through the door.
Every missing admission represents more than a lost ticket. It also means fewer high-margin concession sales — the popcorn, drinks, and candy fundamental to theatre economics.
Meanwhile, average ticket prices have increased about +24% since 2019, while overall inflation has risen roughly +30%. And exhibitors haven't fully passed those inflationary increases along to moviegoers.
Fewer customers. Fewer concession transactions. Costs rising faster than ticket prices. That's margin compression — and smaller theatres have less volume over which to absorb it.
A Different Marketplace
So why aren't smaller theatres recovering at the same pace?
There's no single answer, and the numbers don't establish cause and effect. But today's theatrical marketplace looks very different from 2019 in ways that can disproportionately affect smaller theatres.
Start with product.
We have -11% fewer wide-release films than in 2019, marking the seventh consecutive year wide releases have failed to return to 2019 levels.
A handful of enormous blockbusters can drive the national box office. But they can't fill a two-, three-, or four-screen theatre's calendar 52 weeks a year.
Smaller theatres depend on a steady cadence of broadly available commercial films.
Then there's the theatrical window. It has improved to approximately 41 days, which is encouraging, but remains less than half the 91 days of 2019. And smaller markets can take longer to discover and build an audience for a film.

The marketplace has changed: fewer wide releases, shorter windows and pricing that has not kept pace with inflation.
For a Small Theatre, Every Screen-Week Matters
And then there's simple math.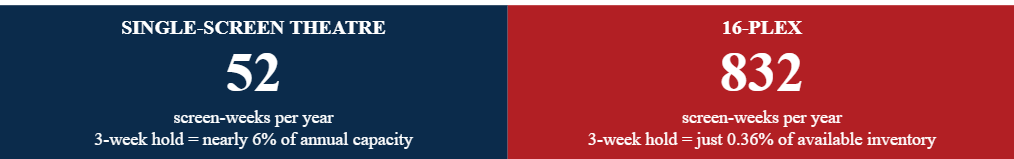
The larger theatre doesn't just have more screens — it has dramatically more flexibility to move films around, accommodate longer holds, double-screen a blockbuster and still make room for something new.
For a small theatre, every screen-week matters.
Which brings us back to something ICA has been saying for some time:
One-size-fits-all business practices don’t have one-size-fits-all consequences.
A three-week hold, a thin release calendar or a shorter window simply means something different when you have two screens instead of twenty.
A Stronger Industry Requires a Broader Recovery
None of this diminishes the progress our industry is making. The recovery is real — and after the last several years, we should be excited about it.
But we also shouldn't allow a strong national number to obscure the very real financial challenges many theatres are still facing.
The average industry screen is now generating more box office than it did in 2019.
The average small-theatre screen is not.
If we want a truly healthy theatrical ecosystem, getting the national box office back isn't enough.
More movies. Longer windows. Reasonable holds. Greater flexibility.
Different theatres are different businesses, serving different communities. A stronger industry requires a broader recovery.